Keeping German business records: retention periods and a traceable process
The retention period depends on the type of record. A reliable process connects originals, postings, changes and controlled review of retention deadlines.
Quick answer
German business records do not all share one retention period. Books, inventories and annual accounts generally require ten years, accounting vouchers eight years, and commercial or business correspondence six years. Check the starting event, special rules and unresolved tax matters before deleting anything.
Key takeaways
- Do not lose the relationship between originals and postings.
- Correct posted entries traceably instead of overwriting them.
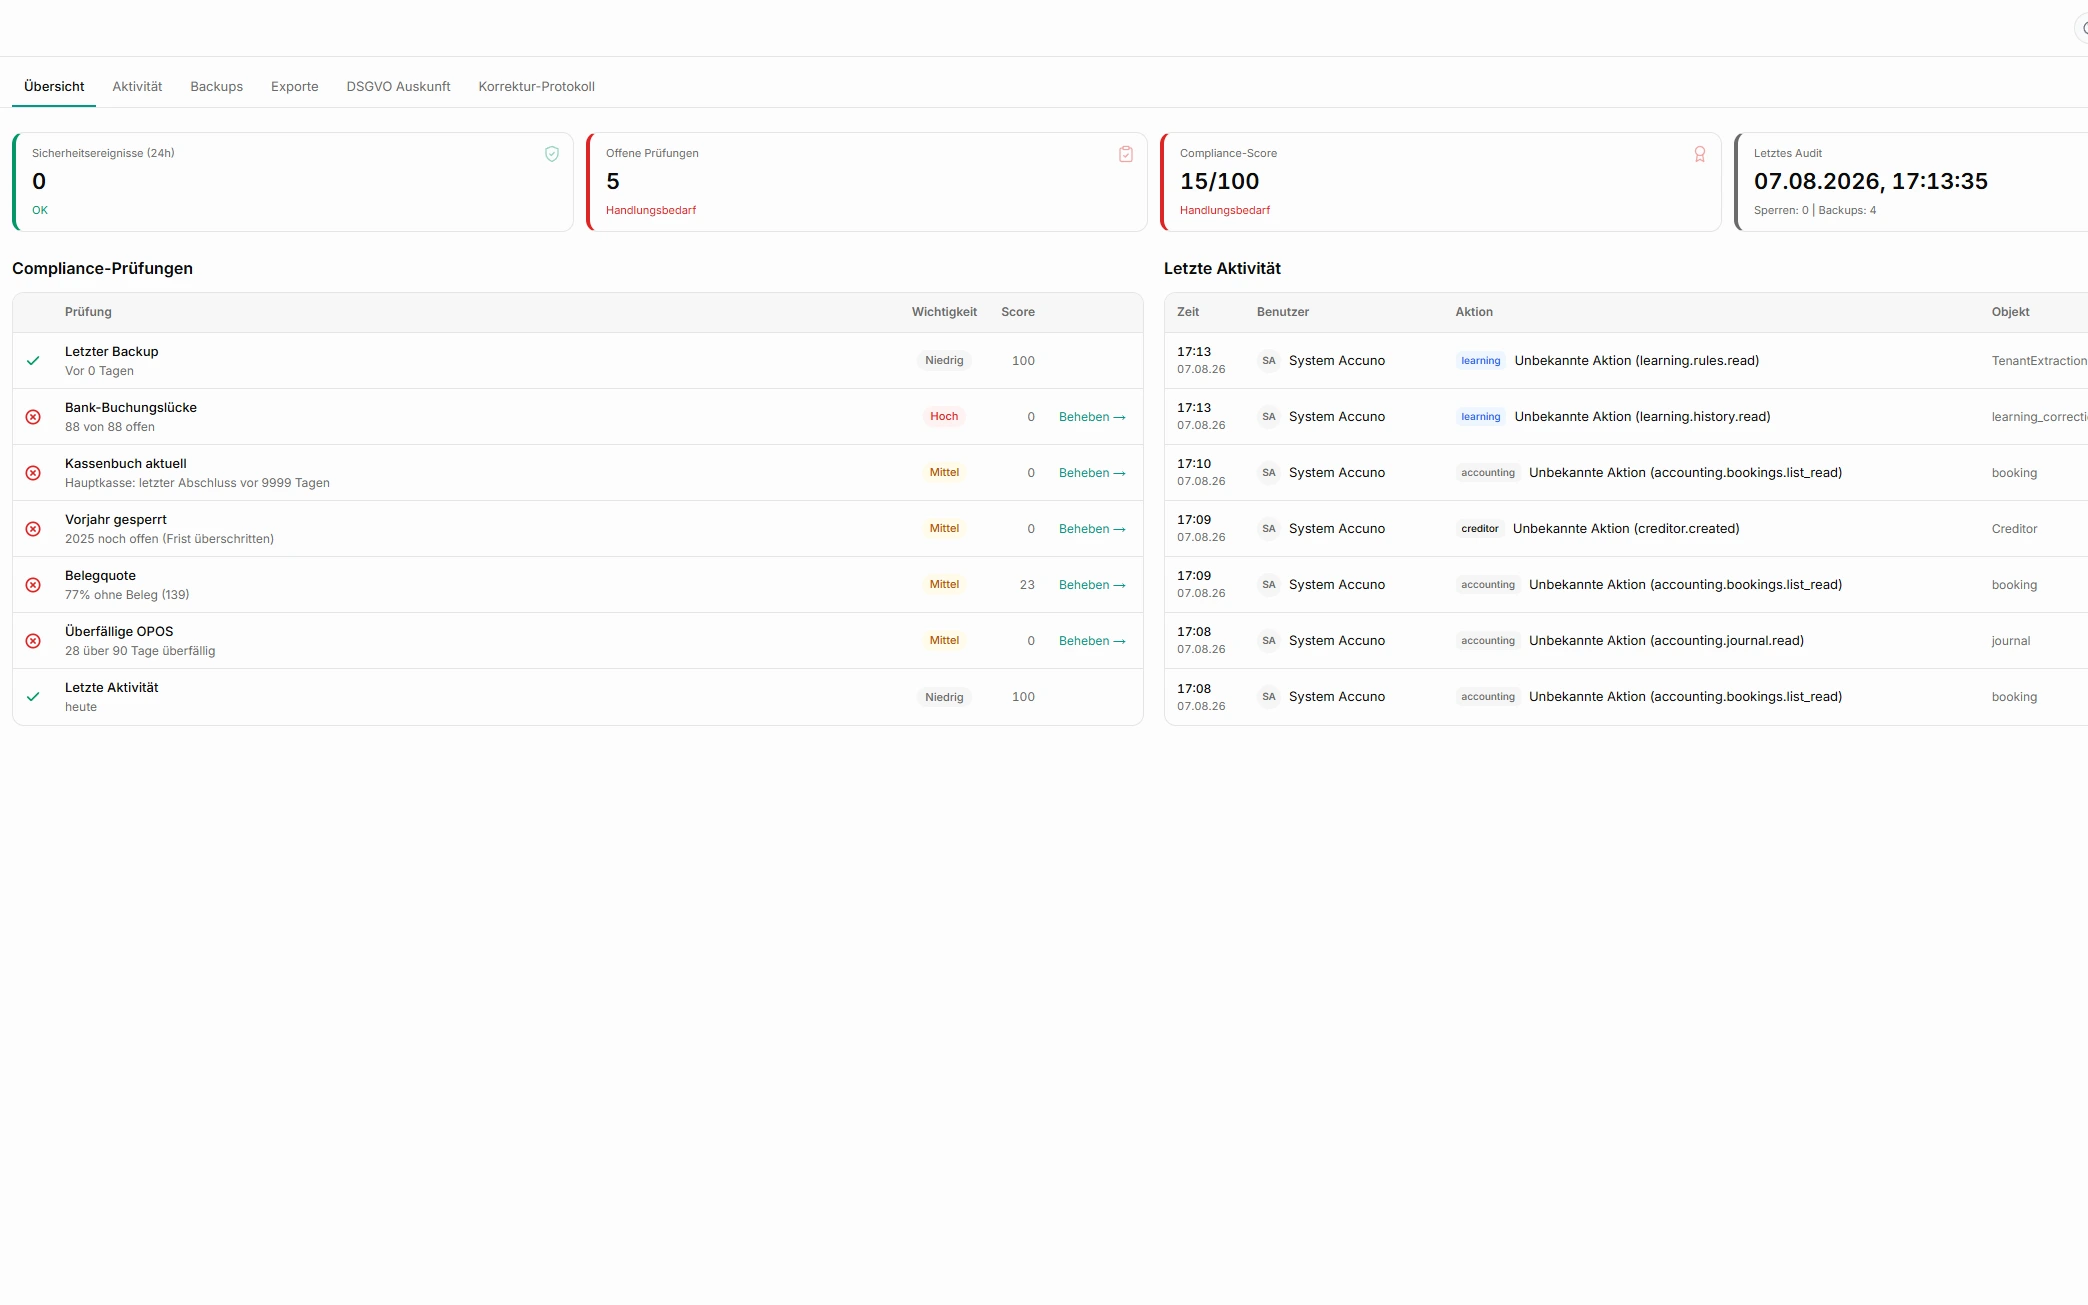
- Access, outages, exports, and deletion belong in the documented procedure.
Traceability starts at intake
Keep the original record, intake time, source channel, processing status, and the relationship to every resulting posting. Renaming, moving, or extracting a file must not sever that connection.
A central repository with explicit ownership and statuses is more reliable than private inboxes. A document without a clear review state remains an open process even when the file itself has been stored.
Do not overwrite corrections
Errors are normal; invisible changes are the risk. Posted entries should be corrected through a traceable reversal and replacement rather than silent overwrites.
Preserve the original state, correction, reason, time, and responsible actor. Changes to master data and permissions can also affect accounting outcomes and belong in appropriate audit evidence.
Sources and further information
Four controls that help
Useful controls address a concrete risk and remain usable in day-to-day work. They should make exceptions easier to inspect rather than adding a checkbox without evidence.
- Check duplicates across invoice number, counterparty, and amount.
- Enforce period and posting-lock rules before final posting.
- Restrict exports, reversals, and master-data changes by role.
- Run recurring test exports with record links and change evidence.
Document the real process
Document the systems and intake channels actually used, who performs each step, how outages and exceptions are handled, and when records are exported or deleted. A procedure that describes an idealized process is not useful evidence.
The applicable legal and tax requirements depend on the business and should be reviewed professionally. Software can support controls and records, but it does not transfer responsibility for the process away from the company.
Sources and further information
How long must business records be retained?
The overview describes the main ordinary periods under section 147 AO and section 257 HGB as checked in September 2026. Classify a document by its function: an email can be business correspondence and an invoice is normally an accounting voucher. File format alone does not determine the period.
The eight-year voucher period does not shorten the retention of books or annual accounts to eight years. Section 257 HGB retains ten years for vouchers of certain regulated businesses, particularly in financial services and insurance. Other special requirements need separate review.
| Typical record | Ordinary period |
|---|---|
| Books, inventories, opening balance sheets and annual accounts | 10 years |
| Accounting vouchers, including incoming and outgoing invoices | 8 years |
| Received and sent commercial or business correspondence | 6 years |
| Other tax-relevant records under section 147 AO | generally 6 years |
Sources and further information
The period starts at year-end: an invoice example
The period generally starts at the end of the relevant calendar year. The event depends on the document: the last book entry, creation of the voucher, or preparation or approval of the accounts under the applicable provision.
For example, an ordinary voucher is created in June 2026. Its eight-year period starts at the end of 31 December 2026 and ordinarily runs through 31 December 2034. Destruction could be considered from 1 January 2035 at the earliest, provided no longer obligation applies. Annual accounts for 2026 may instead be prepared in 2027; the financial year printed on the document is not enough to determine the deadline.
Sources and further information
An elapsed period is not automatic deletion approval
Under section 147 AO, retention does not expire to the extent that records remain relevant to taxes whose assessment period has not expired. Open audits or proceedings can therefore require longer retention. Other legal duties and the document’s evidential role also need consideration.
We recommend a schedule recording document type, triggering event, period, potential holds and the responsible person. Approve and document disposal decisions. A blanket instruction to delete everything after eight years is unsuitable for a mixed accounting archive.
Sources and further information
Digital retention requires continued readability and usability
A file in an old application is insufficient if it becomes inaccessible after migration. Tax requirements include availability, readability and machine analysis. For structured e-invoices, the structured component must in particular be preserved; a screenshot alone does not replace it.
Before changing systems, test exports of originals, posting references and required evidence. Backups support recovery but do not alone provide a retention process. Document how authorized people can still locate and produce the records years later.
Sources and further information
Related workflows in accuno
These product pages show how accuno supports the workflows described in this guide.
Sources and further information
Editorial note
Prepared by the accuno Editorial Team and reviewed against the listed primary sources and the implemented product scope.
These articles provide general guidance and do not replace legal, tax, or business advice. Confirm your specific situation with a qualified professional.